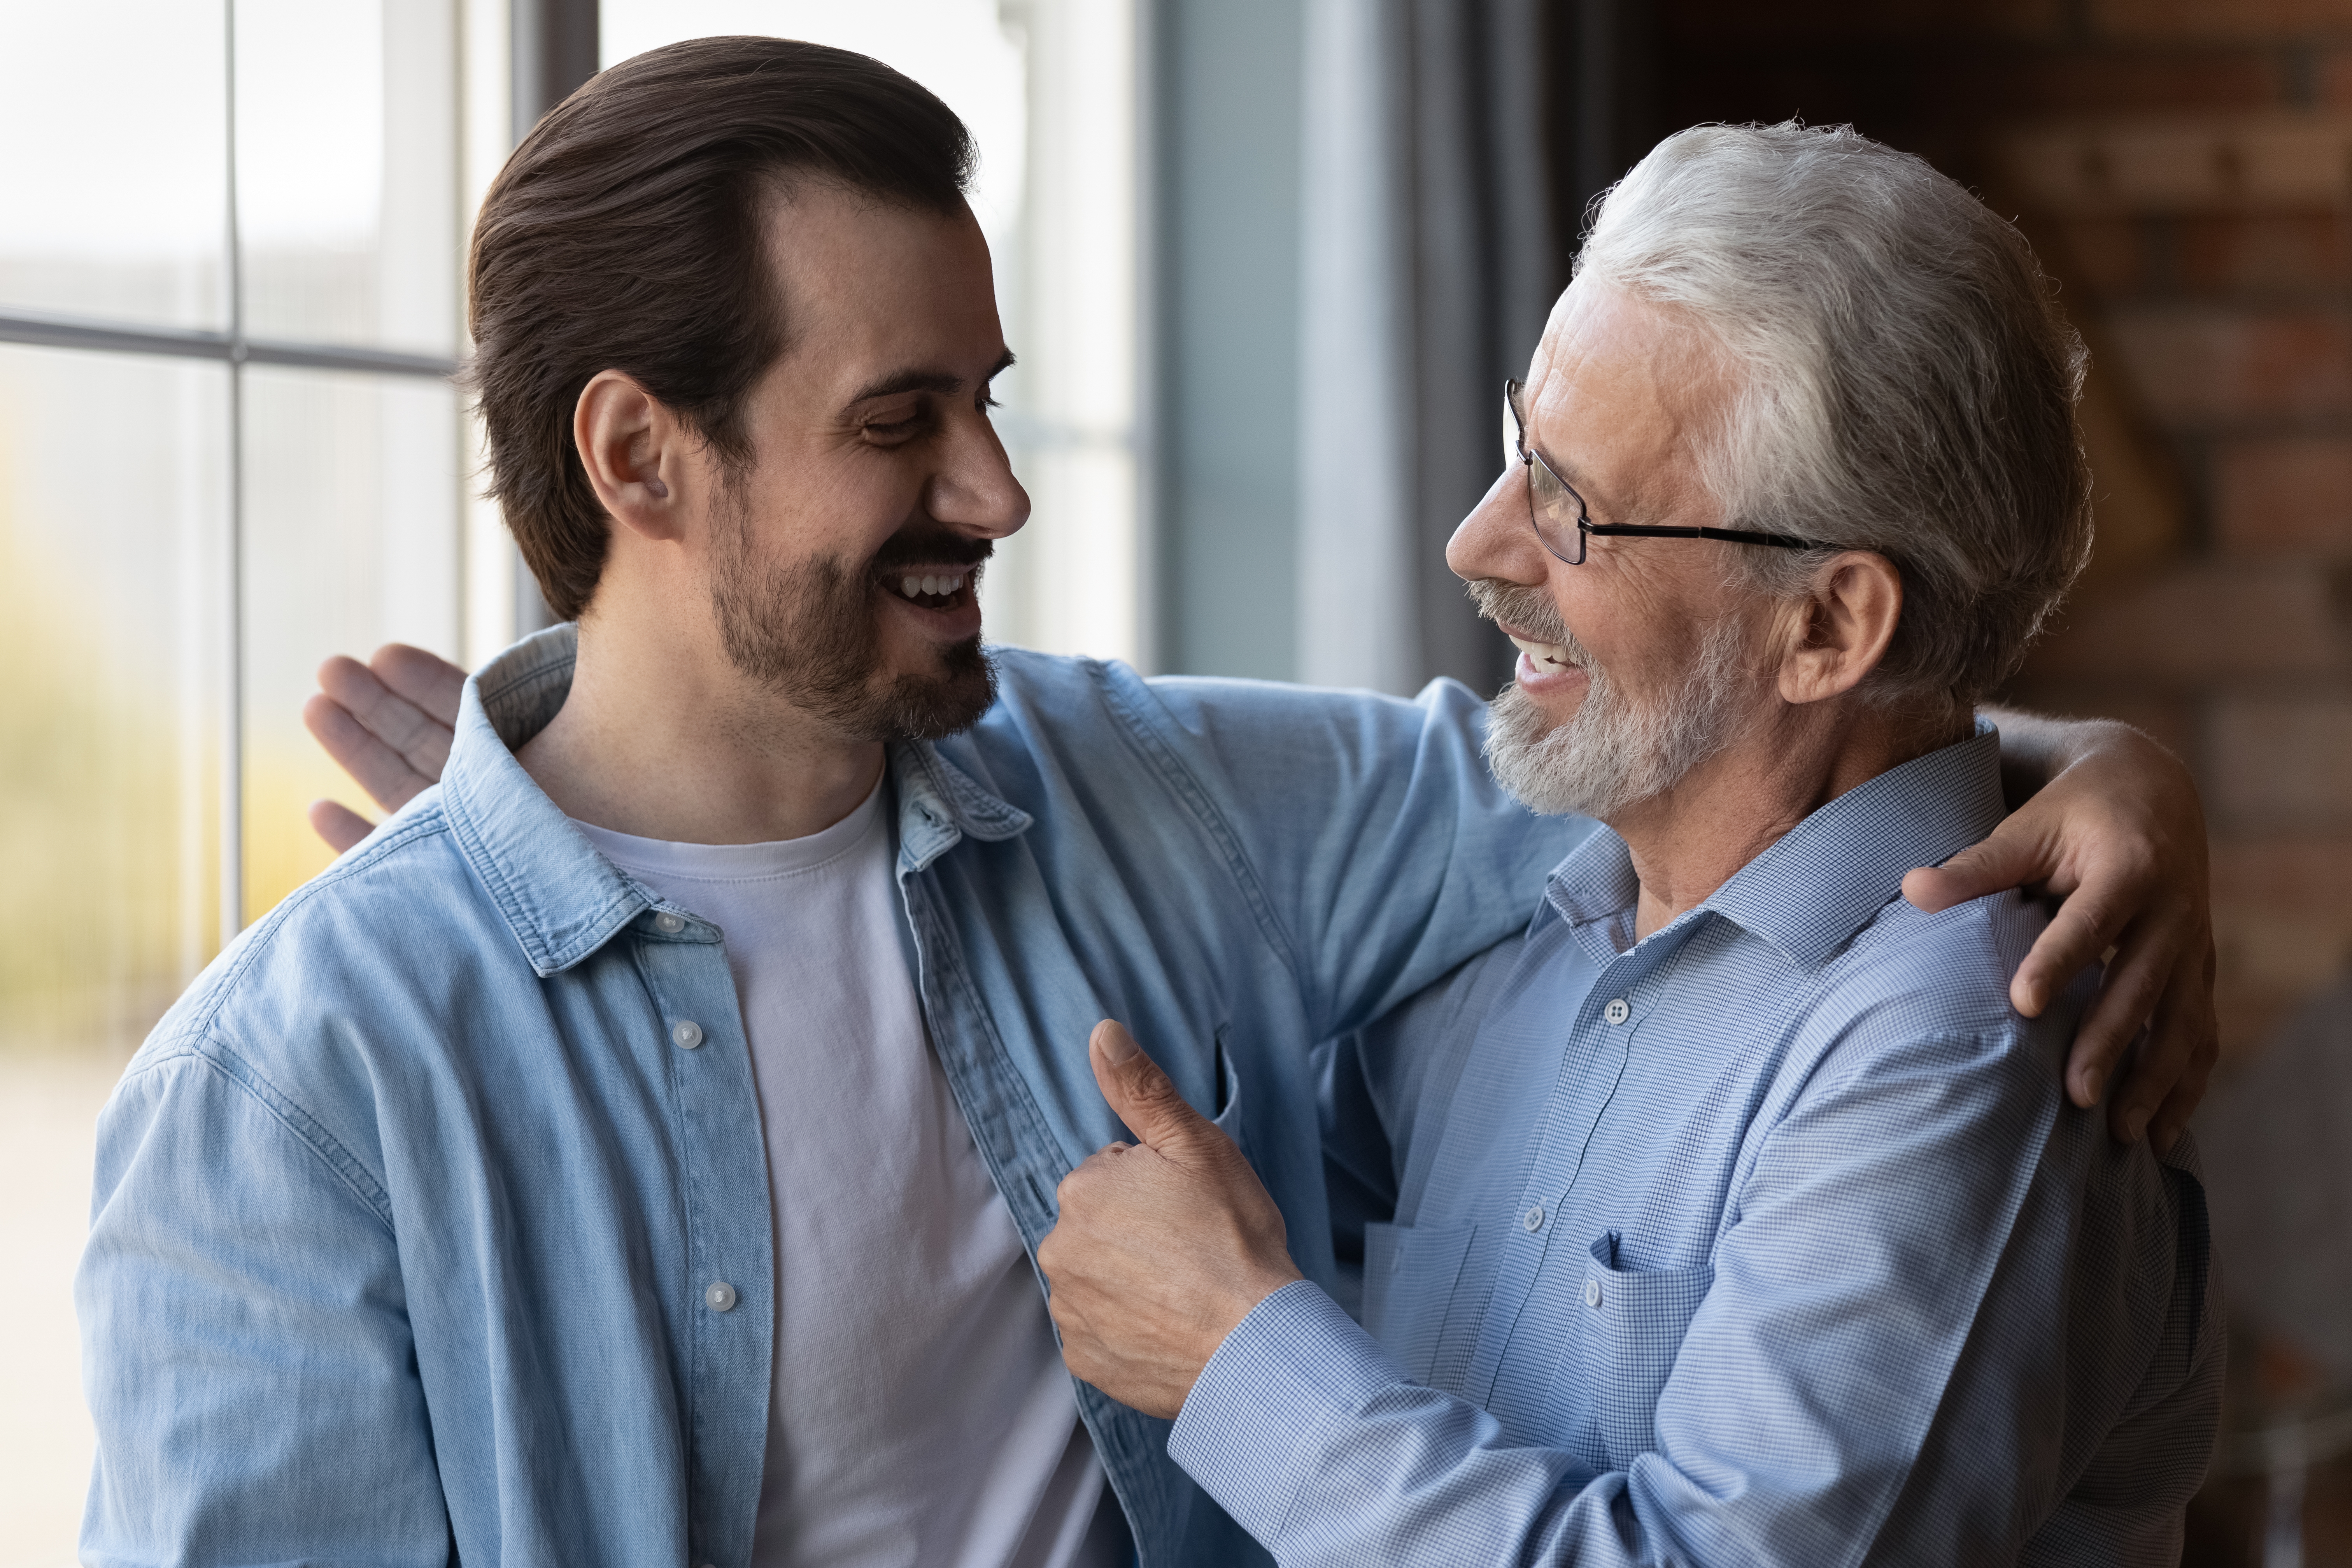
Family businesses are the lifeblood of the UK economy. Working alongside your partner or children can be rewarding and even bring tax advantages. But running one is a delicate balancing act, with emotional ties that sometimes prove complex to unravel.
Around 90% of the UK’s private companies are family run. Alongside the usual business concerns, such as cashflow and making sure it’s well managed, there are other specific challenges. Not least, knowing that those tricky conversations you have during the working day are likely to spill over to the family dining table.
We’re able to advise our clients on several aspects of running a family business, not just financial, so here are five important rules to help you avoid the 5 family business mistakes you may be making:
1. Be clear on your endgame
Starting at the end might sound counterintuitive, but family succession has a reputation for conflict (think Game of Thrones or, indeed, Succession). That’s why it’s so important to be clear from the very beginning about what you want to do.
How and when do you plan to retire? Do you want to pass the business on, or are you selling up instead? If so, how will you pass on the family business, and who is ready to take over?
A new client came to us recently with questions about what might happen when he takes the reins. His parents, now in their 70s, are reducing their involvement, but their company was serving two purposes: a going concern to leave to the family, and the main pillar of their pension pot.
Their son was concerned that, on the current trajectory, there wouldn’t be much wealth left in the business by the time they fully retired. With the aid of some cashflow modelling, we’ve now put both the son, his parents – and the business – on a better footing.
Examples like this show it’s important to be clear on your endgame from the start and have transparent conversations along the way. That way, everybody is working towards the same goal. Handing over or selling a business is just one of several big life events where financial planning can make a real difference.
2. Take care of your basic needs
With this endgame in mind, you then need to make sure you’ve got the basics right.
Do you have the money to run things day-to-day?
Cashflow modelling tools, such as those we use, can provide valuable insights into your cash position and help you make informed decisions that ensure you have enough liquidity to sustain operations and pursue growth opportunities.
Can you get money out of the business if you need it?
This is often a big concern for our clients. A lot of this depends on how your business is set up – for example, are you listed with HMRC as a sole trader, partnership, or a limited company? There are pros and cons to all three. It’s important to remember a family company isn’t a private bank account (you’re usually limited to either taking a salary, dividend payments from profits, a director’s loan, or business-related expenses).
Do you have the right people in place?
Of course, this applies to all businesses, but it’s a pertinent question when approaching it in a family context. Maintaining that balance between family involvement and making sure the business is well-run can mean difficult conversations. It requires owners who are clear-sighted about their limitations and where they might need to bring in outside help.
3. Get your taxes in order
Tax is one of the most important areas we talk to our clients about. Many family business owners worry they’re paying too much. And there are several ways running a family business can help you reduce your liabilities. For example:
Dividends: If you’re a limited company, making your spouse or partner a shareholder means they’re entitled to dividends (as long as the company is in profit). These are taxed at a lower rate than income tax: 8.75% (basic rate), 33.75% (higher rate), and 39.35% (additional rate). There’s also a tax-free dividend allowance, but this was cut to £500 for this current and future tax years.
Salaries: Paying a partner a salary instead is also tax deductible as a business expense, which will reduce your Corporation Tax. Be warned though, it must be a legitimate business function.
Paying a salary can also reduce your national insurance (NI) liabilities. (Sole traders can also go down this route, to reduce their income tax liability.)
4. Have a succession plan – or an exit strategy
We’ve already mentioned the importance of knowing your endgame. This is especially relevant when it comes to tax. Passing on your family business can trigger Inheritance Tax (IHT) or capital gains tax (CGT). Tax-relief options are a regular topic of discussion with our clients. Not having a succession plan can leave your family facing an avoidable tax bill, or even force a sale of the business at the wrong time. Having the right succession plan, or exit strategy if you’re considering selling up, means you can pass down wealth more efficiently to future generations at the right time.
Having the right succession plan, or exit strategy if you’re considering selling up, means you can pass down wealth more efficiently to future generations at the right time. Hear from Alan about how planning ahead changed the way he approached selling his business.
Hold-over relief: By gifting shares in your business to your child, or selling them for less than they’re worth, you can potentially avoid any CGT due (they will have to pay this if they dispose of the asset).
Business relief: You can reduce IHT on your estate by either 50% or 100% with business relief, providing you’ve owned the business assets for at least two years. Business relief can be passed on while you’re still alive or as part of your will.
Trusts: If you’re planning to sell, transferring shares in the company into a trust in the pre-sale process (that is, before the agreement to sell is confirmed) can help mitigate IHT. Trading businesses are usually exempt from IHT as they qualify for 100% business relief. By contrast, if transferred after the sale, the £325,000 IHT limit would apply. Anything above that would be liable for a charge.
5. Embrace change
Finally, if you’re considering passing the baton at some point, it’s important to acknowledge that change is inevitable. New challenges and disruptors will emerge, and the next generation will have their own ideas on how to approach this.
The successful family businesses are those that embrace change, invest in new technology, explore new growth avenues, and are unafraid to consider new approaches when they need to.
Again, as with so much about running a successful family business, communication is the key. Involving people in decision making, keeping them abreast of what’s happening in the business, and discussing the vision, means your family business can go from strength to strength.
Running a family business and want to know more about how you can plan for the future? Get in touch with us today.
Discover more about our dedicated family business team.